Navigating the housing market can feel like solving a moving puzzle, especially when mortgage rates fluctuate. According to Freddie Mac’s Primary Mortgage Market Survey, the average 30-year fixed-rate mortgage stands at 7.40%. For buyers across Greater Cincinnati, that headline figure prompts an important question: What does this mean for my home search, my wallet, and my homebuying timeline?
While interest rate shifts affect national trends, their impact hits home in specific ways across the Queen City—from historic neighborhoods like Over-the-Rhine and Hyde Park to growing suburban hubs in Warren and Clermont counties. Here is a breakdown of how current 30-year mortgage rates are shaping the local Cincinnati market and what you need to know as a buyer.
1. Buying Power and the "Monthly Payment Reality"
When evaluating home affordability, interest rates often play a larger role than purchase price alone. At a 7.40% benchmark, borrowing costs require a close look at monthly financial obligations.
-
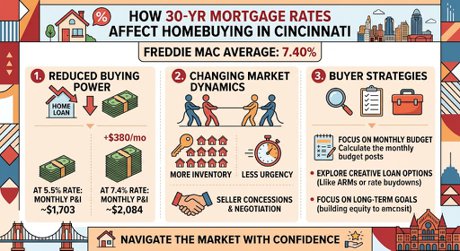
Example Breakdown: For a typical $300,000 home loan:
-
At a 5.5% rate, the monthly principal and interest (P&I) payment is roughly $1,703.
-
At a 7.4% rate, that same loan requires approximately $2,084 per month—an increase of more than $380/month.
-
In Greater Cincinnati, where median home prices remain relatively stable with modest, healthy growth, higher borrowing costs mean buyers must be strategic about their target price point rather than assuming they can stretch to maximum approval limits.
2. Changing Market Dynamics: Less Urgency, More Negotiation
During the record-low rate era, buyers in Cincinnati frequently faced hyper-competitive bidding wars, waiving contingencies and paying well over asking price.
With rates at current levels, market leverage has moderated into a more balanced dynamic:
-
Inventory Growth: Housing inventory across Ohio and Greater Cincinnati has gradually expanded. Buyers have slightly more options and time to evaluate properties before making an offer.
-
Seller Concessions: Sellers are more open to negotiating closing costs, repairs, or financing incentives.
-
Rate Buydowns: Temporary buydowns (such as a 2-1 buydown) or permanent rate buydowns financed through seller credits have become popular strategies to lower initial monthly payments without forcing sellers to make steep list price cuts.
3. Strategies for Today's Cincinnati Homebuyer
If you are planning to purchase in Cincinnati, current rates don't mean you need to hit pause on your plans. Instead, adjust your approach using these tactical steps:
-
Focus on the Monthly Budget, Not Just List Price Partner with a trusted local lender to get pre-approved and establish a comfortable maximum monthly payment—factoring in property taxes (which vary by county across Hamilton, Butler, and Warren counties) and homeowners insurance.
-
Explore Creative Loan Products Work with your loan officer to evaluate fixed-rate loans alongside adjustable-rate mortgages (ARMs), state-specific first-time buyer assistance programs (such as OHFA programs), or temporary rate buydown structures.
-
Marry the House, Date the Rate Waiting for interest rates to drop carries the risk that home prices continue to appreciate in the meantime. Securing a home that meets your lifestyle goals now allows you to start building equity, with the option to evaluate a refinance down the road if market rates improve.
-
Refine Your "Must-Haves" vs. "Nice-to-Haves" If borrowing costs limit your budget in a specific neighborhood, expanding your search radius to adjacent Cincinnati communities or considering homes that need light cosmetic updates can unlock better value.
Final Thoughts
Mortgage rates are just one variable in the homebuying equation. While elevated rates require extra financial planning, Cincinnati remains one of the more accessible and stable housing markets in the region. By understanding your buying power, leveraging negotiation opportunities, and focusing on long-term lifestyle goals, you can navigate today's market with confidence.